Currently, when a resident Indian buys a house, flat or plot from a Non Resident Indian, the buyer cannot just use their PAN like they would in a normal resident-to-resident deal. A resident buyer purchasing property from an NRI property seller has to deduct TDS under the tax provision meant for non-resident sellers, and to do that, they currently need a TAN, a Tax Deduction and Collection Account Number, which is completely separate from PAN and involves its own application process.
For someone buying a single flat, once in their life, applying for an entirely new tax account just to complete one purchase always felt excessive. It meant extra forms, extra waiting time, and a compliance identity you would probably never use again after the deal closed.
What actually changes after October 1
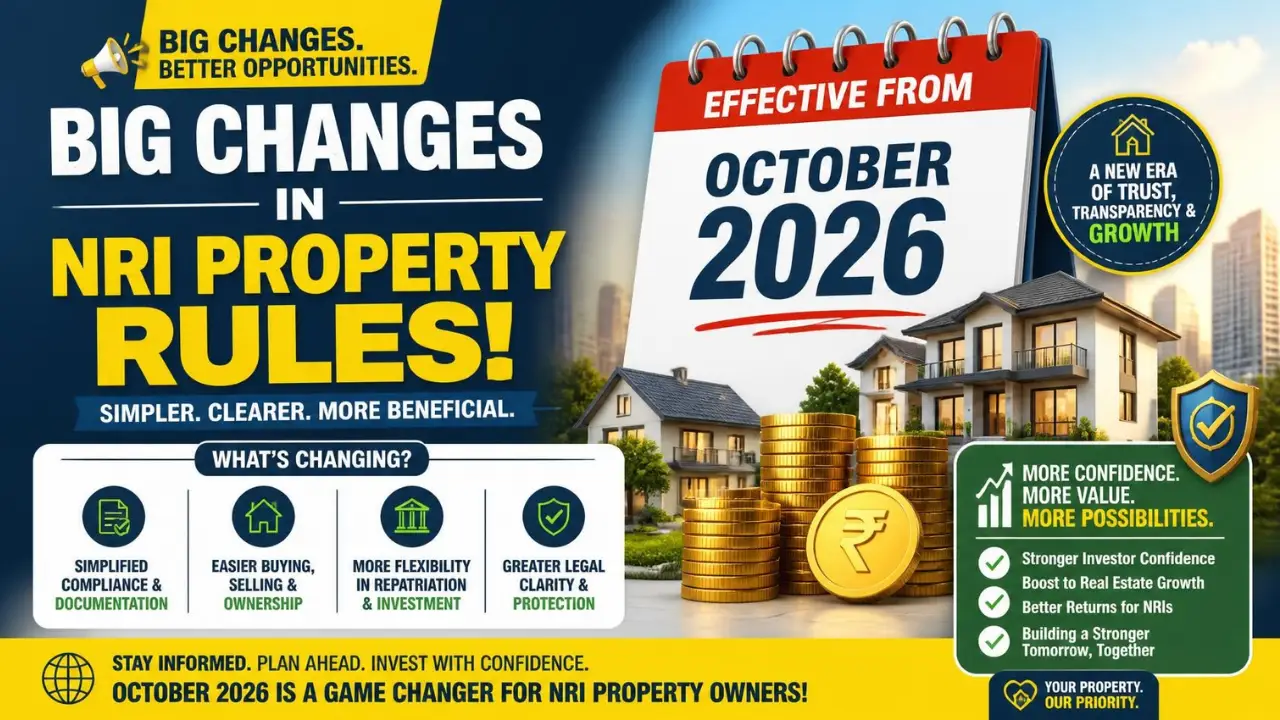
From October 1, 2026, resident buyers will no longer need a separate TAN when deducting TDS on payments for immovable property purchased from an NRI. Instead, the buyer will be able to use their own PAN and report the deduction through a prescribed PAN-based challan cum statement, similar to what already happens in a regular resident-to-resident property purchase.
In plain language, this brings the process of buying property from an NRI property a lot closer to the process of buying from a resident seller, and it takes a real chunk of the compliance burden off the buyer's shoulders. But, and this part matters, it is not a blanket free pass for everyone. The relief applies specifically from October 1, 2026, and only to resident individual and Hindu Undivided Family buyers. If you are buying today, before the cutoff, or if you happen to be a company or a partnership firm buying at any point, the old TAN-based process still applies to you regardless of the date.
There is also a cut-off worth remembering if you are mid-transaction. The existing rules continue to apply wherever the NRI property seller actually receives the sale consideration before October 1, 2026. So buyers completing payment before that date still need to go through the current TAN-based TDS process, even if the deal was negotiated earlier. If your registration or payment date lands right around the changeover, this is worth double-checking with your CA rather than assuming either way.
The TDS rate for NRI sellers is not changing
Here is where people often get confused, understandably. The rule change is only about paperwork, not about how much tax actually gets deducted.
The rate stays at 12.5 percent for long-term capital gains, where the property has been held for more than 24 months, plus applicable surcharge and cess. Short-term gains continue to be taxed at regular slab rates. And if the NRI property seller does not provide a PAN at all, the rate jumps sharply to 20 percent.
There is also no safety net of a minimum threshold here, unlike resident-to-resident property deals. For NRI property sellers, there is no minimum limit before TDS needs to be deducted, while resident Indian sellers enjoy a threshold of Rs 50 lakh before TDS even applies. So whether the flat costs nine lakhs or nine crores, TDS kicks in from the very first rupee whenever the seller is an NRI.
Why this matters if you are buying or selling right now
If you are an NRI planning to sell property in India before the end of September, timing genuinely matters here. NRIs looking to close a sale before September 30 should factor in the time it takes for the buyer to apply for a TAN and complete the full TDS compliance process within the transaction timeline. Wait until after October 1 instead, and if the buyer qualifies as an individual or HUF, that particular delay simply disappears from the picture.
If you are the one buying, do not assume this removes your tax responsibility altogether. If the required TDS is not deducted or deposited correctly, the buyer can be treated as being in default, becoming personally liable for the TDS amount itself, along with interest and a penalty that can equal the TDS amount. The paperwork is getting lighter. The obligation to deduct and deposit the tax correctly is not going anywhere.
The bottom line
This is one of those quiet policy tweaks that will not make front-page news but will genuinely make life easier for thousands of ordinary families buying property from relatives or sellers settled abroad. One less form, one less office visit, one less avoidable delay in a process that already comes with enough moving parts.
Just remember the fine print. NRI property sale rules kick in from October 1, 2026. It applies to resident individual and HUF buyers. And it changes how tax gets reported, not how much of it you owe. Everything else about buying property from an NRI, including the higher TDS rates and the need to get the numbers exactly right, stays the same as before.